
IBAN Verification
Overview
IBAN Verification uses SEPA-based transactions to confirm that a client is the holder of a valid bank account, and that the account holder name matches the provided identity.
This lightweight verification method increases conversion while supporting your regulatory and fraud-prevention requirements.
Benefits
- Higher conversion: Automated verification minimizes manual checks and reduces client drop-off.
- Verified ownership: Confirms that the submitted bank account belongs to the verified client.
- Flexible configuration: You can use IBAN Verification together with Money Transfer, or as a single verification method.
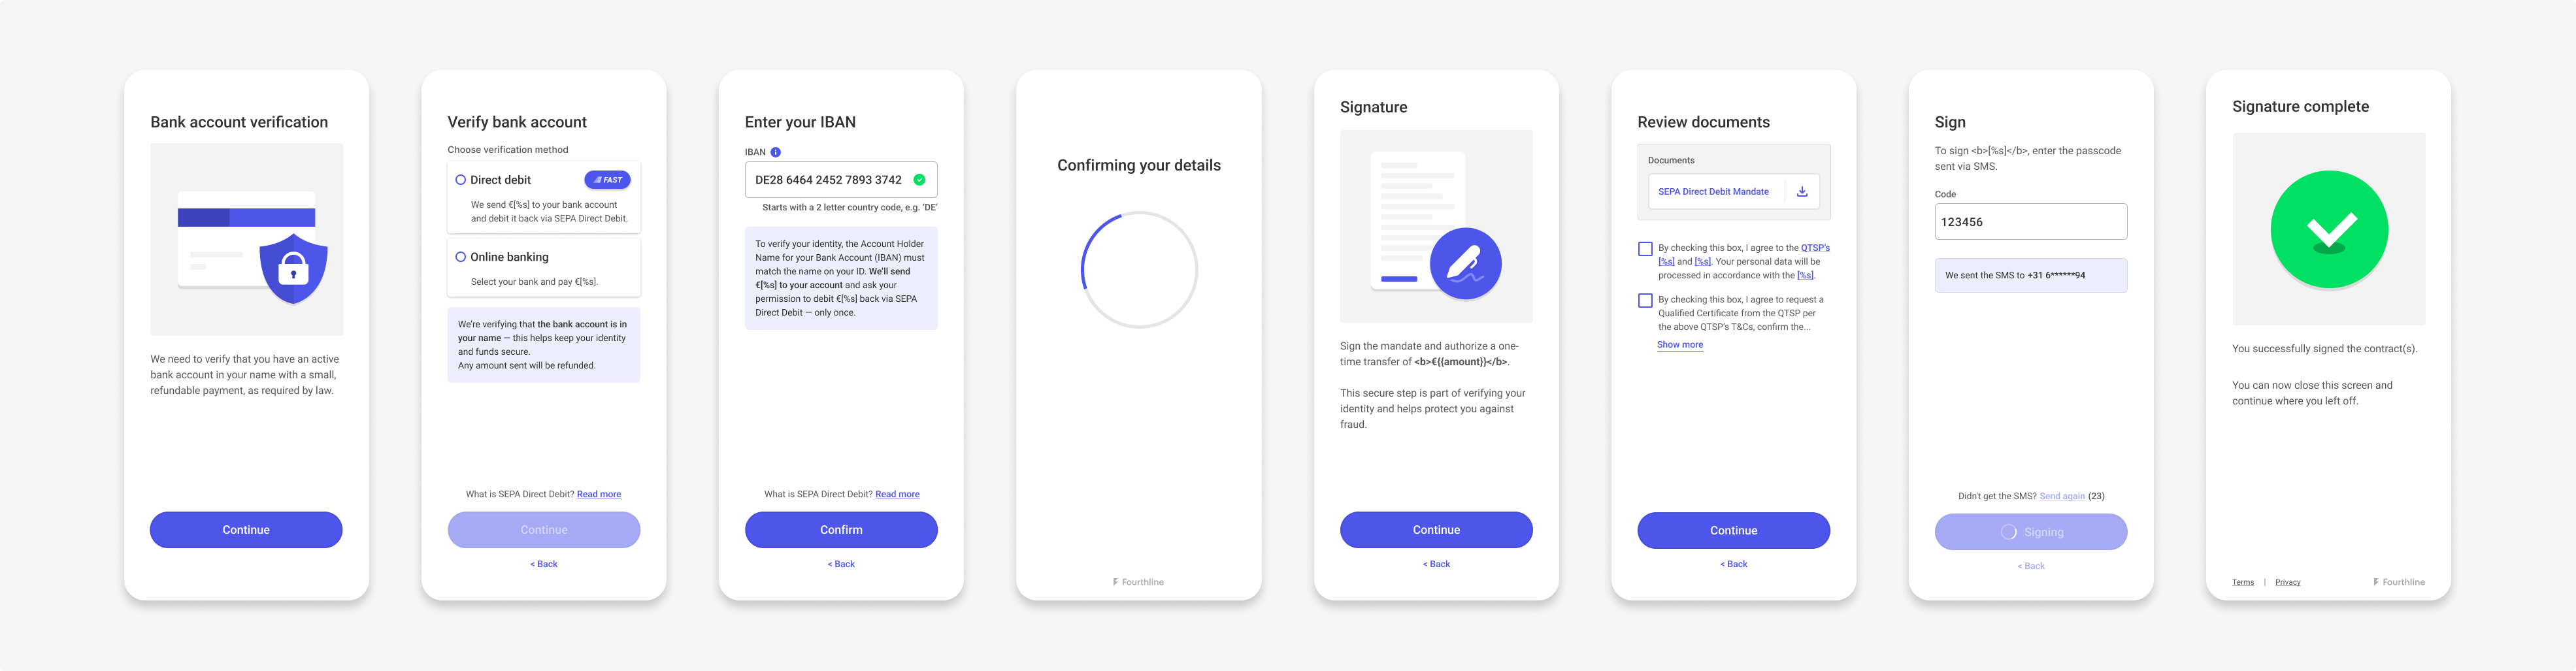
Mobile SDK with two configuration flows
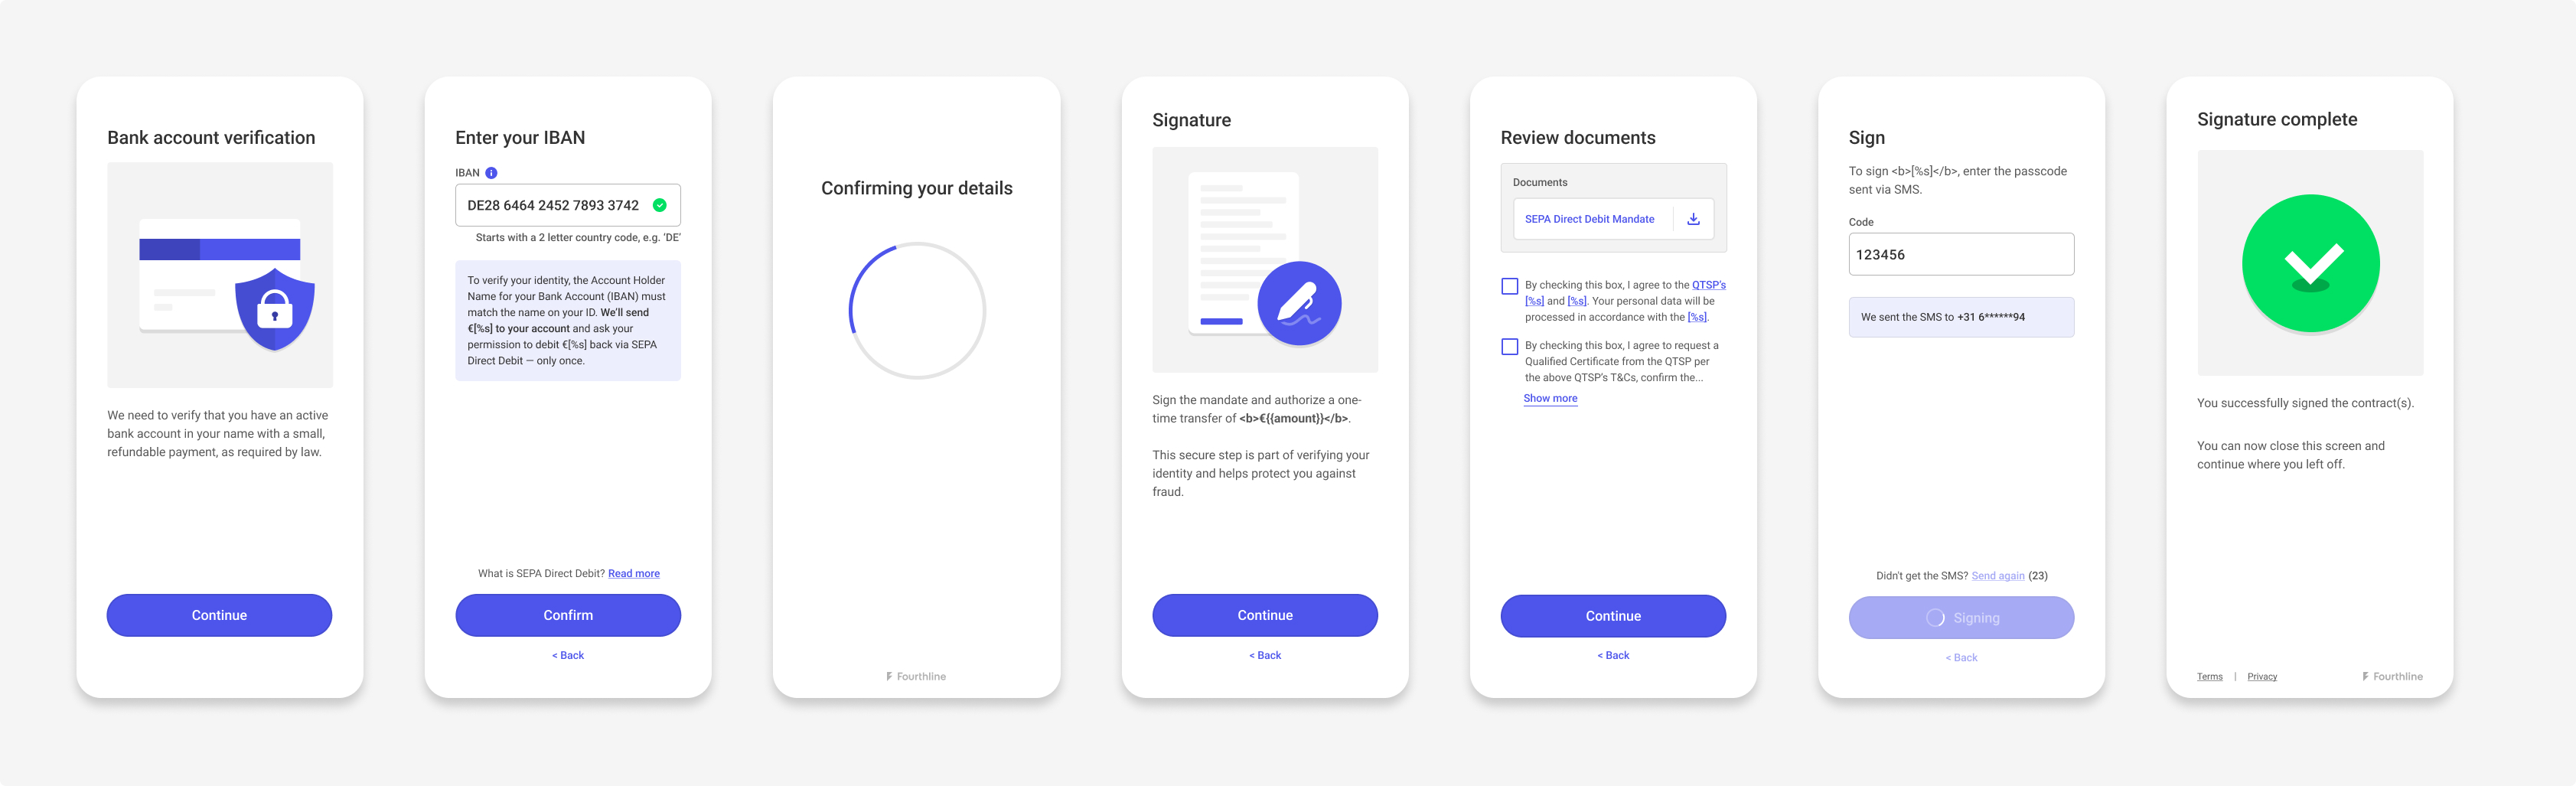
Mobile SDK flow for IBAN Verification
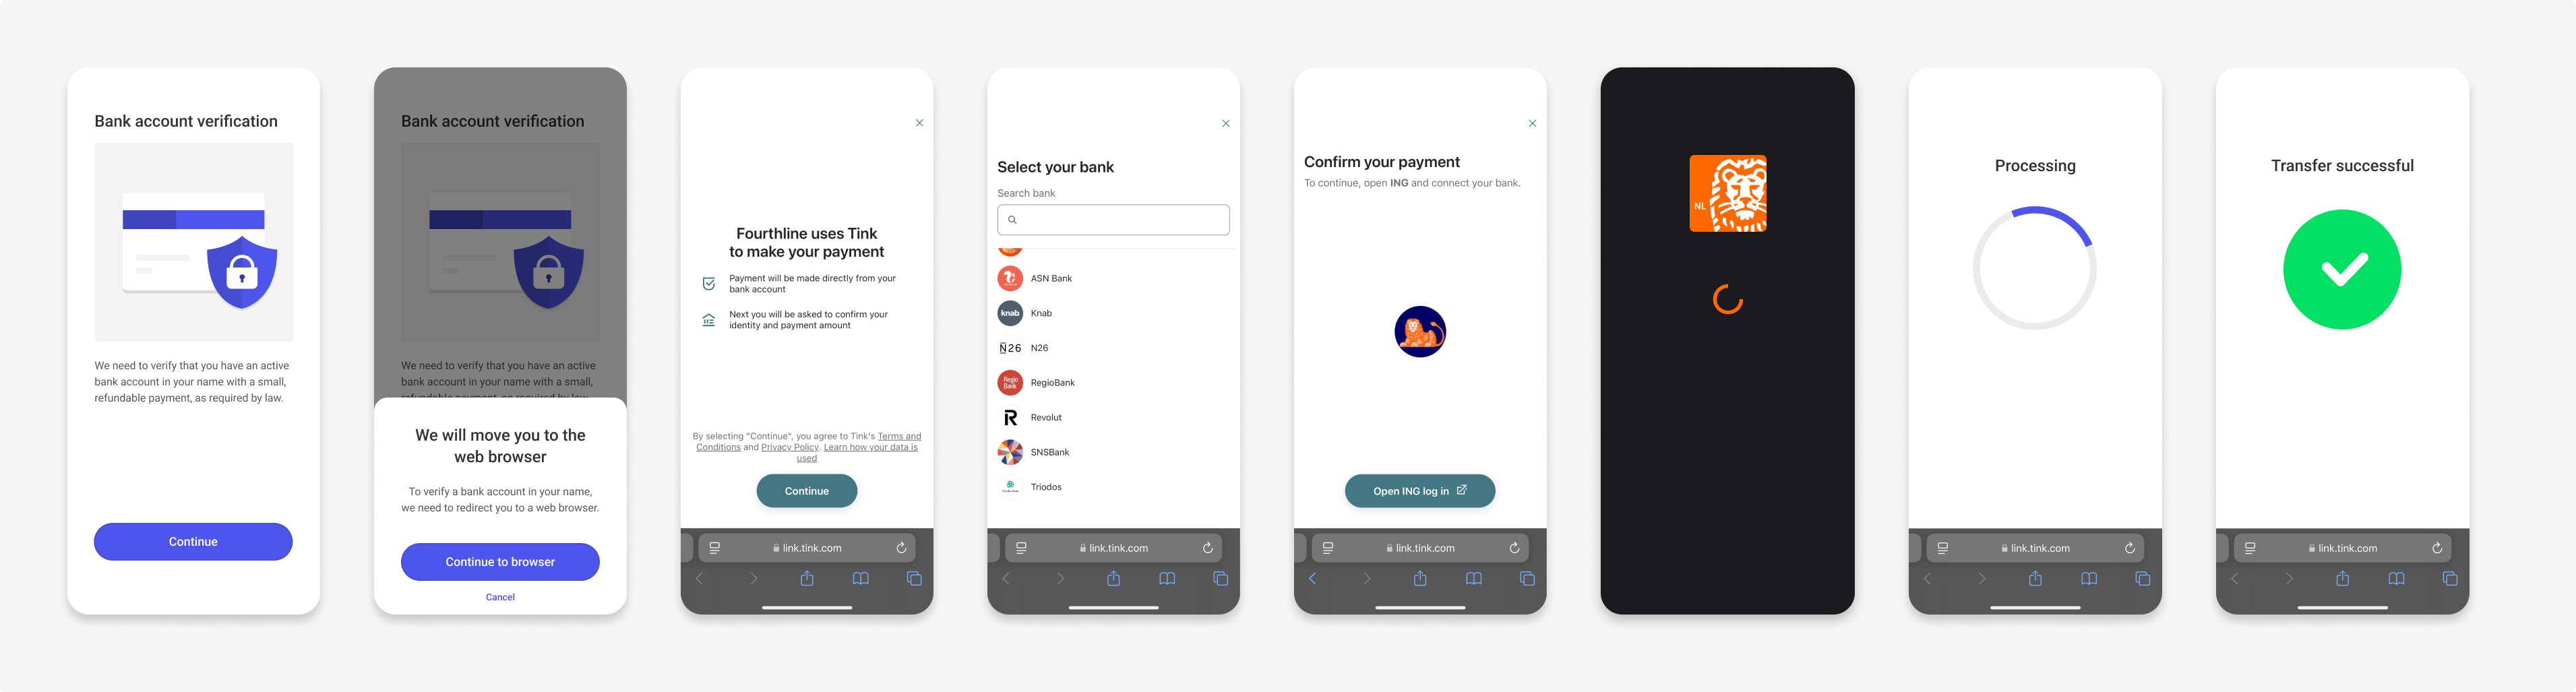
Mobile SDK flow for Money Transfer
How it works
Objective
Verify that the client holds a bank account in their own name with a regulated European bank.
This verification method uses a combination of an IBAN name check and reference transactions to confirm account ownership.
This approach aligns with § 12 Absatz 1 Nr. 3 of the German Anti-Money Laundering Act.
Process
IBAN Verification confirms that the client is the legitimate account holder of the provided IBAN.
Prerequisite
Update your integration to the latest SDK version to enable IBAN Verification.
1. IBAN name check
During onboarding, the client provides their IBAN and name.
Fourthline initiates the IBAN name check to verify whether the provided name matches the account holder name associated with the IBAN. Possible results:
match- The provided name matches the account holder name.no_match- The provided name does not match the account holder name.
If the result is a no_match, the client cannot complete the journey on the mobile device and therefore cannot create a SEPA Direct Debit mandate.
2. SDD mandate
If the IBAN name verification is successful, a SDD mandate is created and prefilled with:
- Verified IBAN
- Address
- Account holder name
The client must review and sign the mandate to continue.
3. Reference transactions
To verify account ownership, Fourthline performs two €1.01 reference transactions on the provided IBAN:
- SEPA Credit Transfer (SCT): sends funds to the account to confirm it is active and reachable.
- SEPA Direct Debit (SDD): collects funds from the account to confirm debit authorization. The SDD requires the client to sign a direct debit mandate before the transaction can be executed.
These transactions are initiated in parallel and typically complete within 2-3 working days. They do not block the onboarding flow.
SEPA DD transactions are denominated in EUR and require a bank that supports the SEPA scheme.
SEPA coverage
The following table lists the SEPA countries and territories currently covered by IBAN Verification.
You can see which markets are already supported, which are on the roadmap, and which are not yet supported.
| Country | ISO Code | Status |
|---|---|---|
| Austria | AUT | Supported |
| Belgium | BEL | Supported |
| France | FRA | Supported |
| Germany | DEU | Supported |
| Italy | ITA | Supported |
| Luxembourg | LUX | Supported |
| Netherlands | NLD | Supported |
| Portugal | PRT | Supported |
| Slovakia | SVK | Supported |
| Spain | ESP | Supported |
| Albania | ALB | On roadmap |
| Andorra | AND | On roadmap |
| Bulgaria | BGR | On roadmap |
| Croatia | HRV | On roadmap |
| Cyprus | CYP | On roadmap |
| Czech Republic | CZE | On roadmap |
| Denmark | DNK | On roadmap |
| Estonia | EST | On roadmap |
| Finland | FIN | On roadmap |
| Greece | GRC | On roadmap |
| Hungary | HUN | On roadmap |
| Iceland | ISL | On roadmap |
| Ireland | IRL | On roadmap |
| Latvia | LVA | On roadmap |
| Liechtenstein | LIE | On roadmap |
| Lithuania | LTU | On roadmap |
| Malta | MLT | On roadmap |
| Monaco | MCO | On roadmap |
| Norway | NOR | On roadmap |
| Romania | ROU | On roadmap |
| San Marino | SMR | On roadmap |
| Slovenia | SVN | On roadmap |
| Sweden | SWE | On roadmap |
| United Kingdom | GBR | On roadmap |
| Vatican City | VAT | On roadmap |
| Switzerland | CHE | Not supported |
| Poland | POL | Not supported |
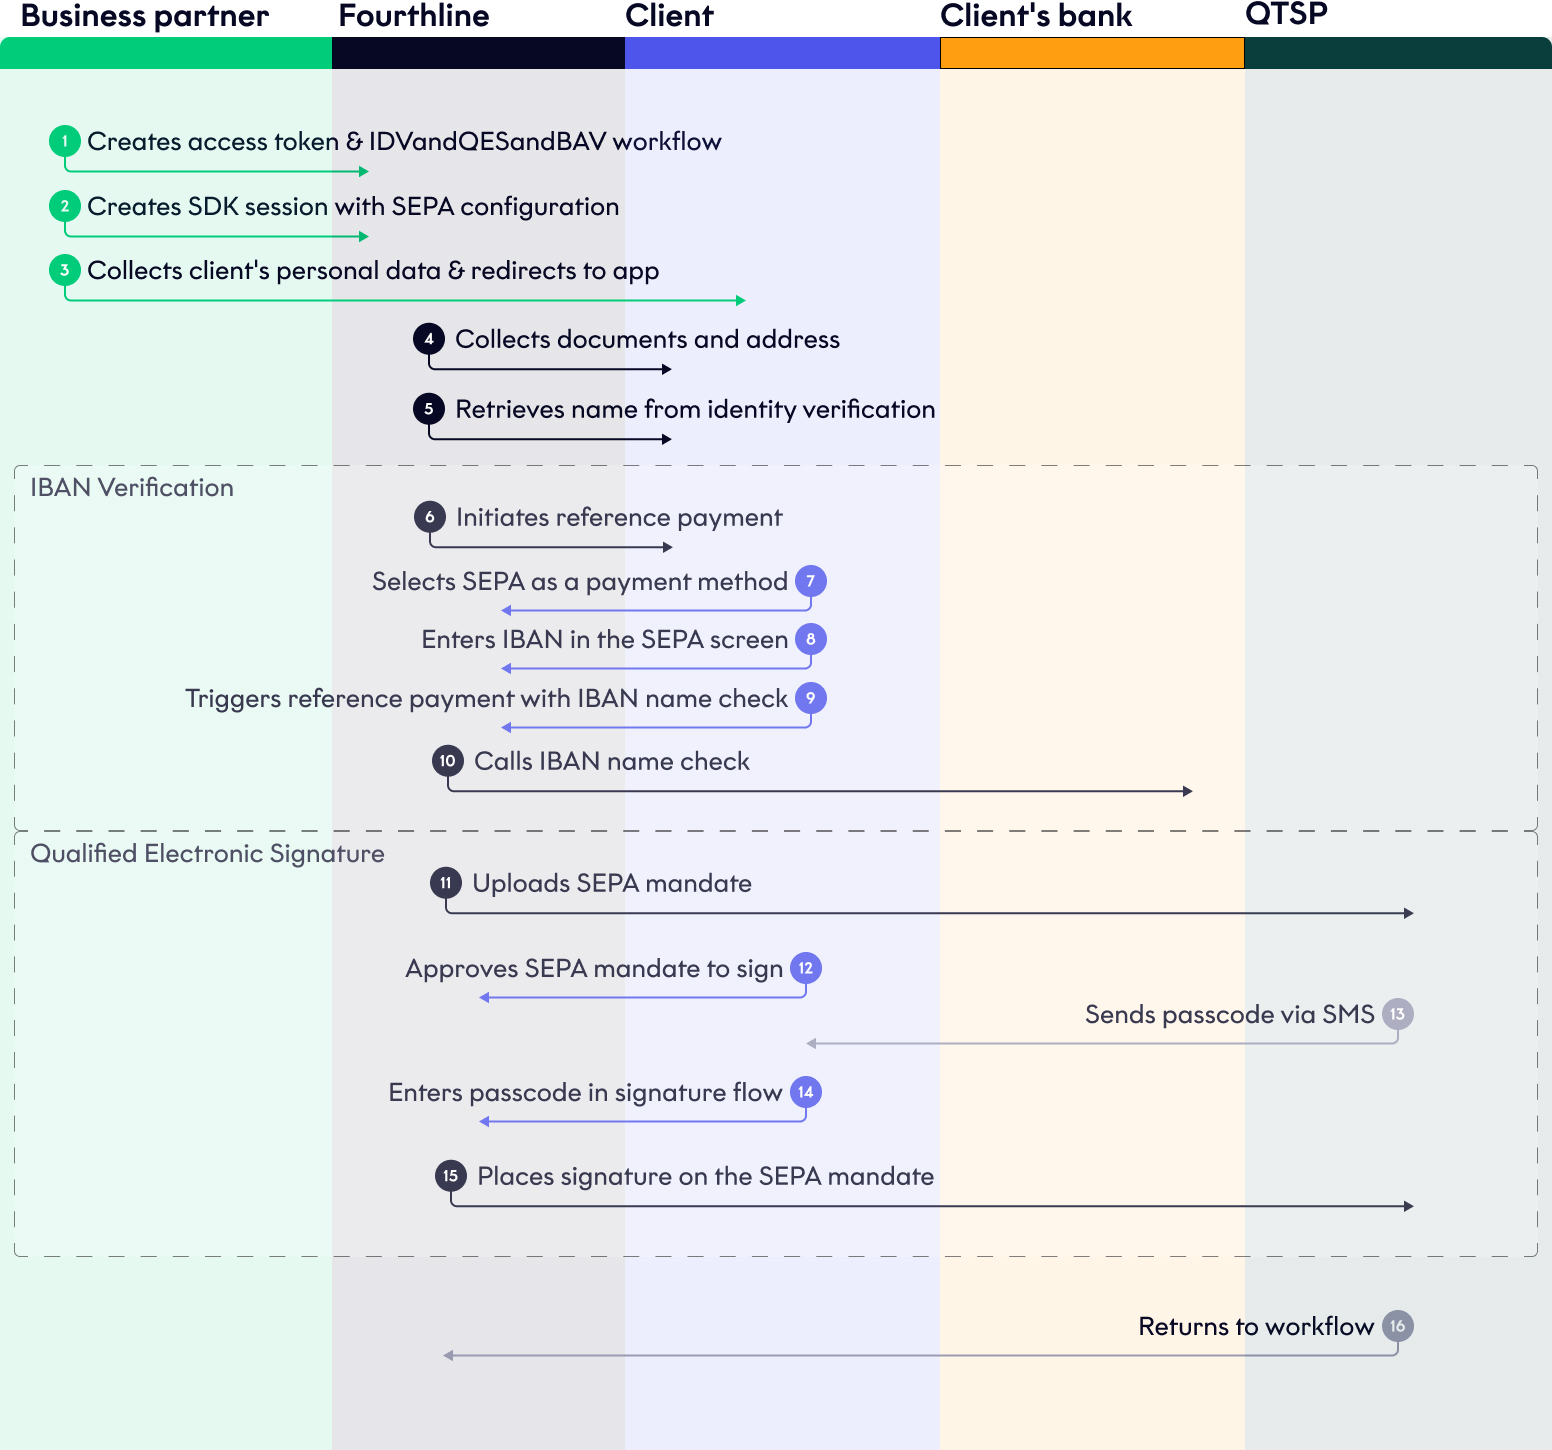
Flow
The flow is as follows:
FAQ
What’s the benefit of using SEPA DD?
SEPA Direct Debit serves as proof of bank account ownership and strengthens identity verification.
What is the difference between SEPA DD and SCT?
| Full term | Abbreviation | Description |
|---|---|---|
| SEPA Direct Debit | SEPA DD | Fourthline collects funds from the client's account (requires a mandate). |
| SEPA Credit Transfer | SCT | Fourthline sends funds to the client's account. |
What is a SEPA mandate?
To create a SEPA DD, Fourthline must first obtain a signed SEPA mandate containing the client's details, after verifying that the IBAN and account holder name match.
Clients can request to cancel a mandate at any time. To do so, they must contact either the business with whom the mandate was established or their bank directly.
When a mandate is canceled, it becomes invalid for future debit requests. To continue accepting payments, a new mandate must be created and accepted by the client.
Fourthline becomes aware of a canceled SEPA mandate when a payment attempt fails. At that point, the mandate is marked as inactive.
What is the processing time?
The transfer and debit are processed automatically, typically within 2–3 working days each.
This timing does not impact the verification flow.
Which SEPA Direct Debit scheme does Fourthline support?
Fourthline supports the SEPA Direct Debit Core scheme, which covers personal bank accounts.
The SEPA Direct Debit B2B scheme is not supported.
Can I use IBAN Verification as a single verification method?
Yes, IBAN Verification can be used as a single verification method, or together with Money Transfer.
Next steps
Learn how to combine IBAN Verification into your German Solution. Contact your Fourthline delivery manager.
Updated 29 days ago